PRISM Q&A CORNER
Yoshiyuki Aikawa , SBC Medical Group Holdings
Q4 2025 Earnings Beat, OrangeTwist Partnership Update, and Growth Strategy
Following a deliberate restructuring year, SBC Medical reports improving unit economics, a $164 million cash position, and an active U.S. partnership. CEO Yoshiyuki Aikawa on what the inflection means and where the company goes from here.
For most of its 25-year history, SBC Medical Group Holdings (Nasdaq: SBC) operated largely out of view of U.S. investors, a Japanese management services organization quietly building what would become the country’s largest aesthetic medical network. That changed in September 2024, when the company listed on Nasdaq, introducing a business profile that is unusual in the U.S. market: capital-light, high-margin, franchise-driven, and profitable at scale.
Over two and a half decades, SBC has grown from a single clinic in Fujisawa, Japan into a network of 283 locations across aesthetic and related medical specialties, serving 6.63 million patient visits annually. The model it built to do that, a management services organization that separates clinic administration from clinical practice, generates EBITDA margins above 40% while remaining capital-light. It is a structure that has proven durable through market cycles, and one the company believes is exportable.
Fiscal 2025 was a year of intentional transition rather than operational stress. The company revised its franchise fee structure and exited non-core businesses, moves that reduced reported revenue but were designed to sharpen the platform for the next phase of growth. Net income still grew 9% and EBITDA margins held above 40%. By the fourth quarter, the underlying business was sending a more encouraging signal: average revenue per clinic visit reached $316, up 11% year over year, reversing a multi-quarter compression trend and indicating that the unit economics the model was built on are beginning to recover.
At the same time, SBC completed a strategic minority investment in OrangeTwist, a U.S.-based premium medspa platform, marking the company’s formal entry into the American market. With $164 million in cash and a D/E ratio of 0.20x, the balance sheet behind that expansion is among the strongest of any small-cap healthcare company currently trading on a U.S. exchange.
Yoshiyuki Aikawa founded SBC Medical over two decades ago as a single clinic in Fujisawa, Japan. He now serves as Chairman and CEO of a publicly listed company with an explicit ambition to build the most trusted medical group in the world. We spoke with him about what the Q4 inflection means operationally, how the OrangeTwist partnership is developing on the ground, and how he approaches deploying a balance sheet that provides more strategic flexibility than the company’s current market capitalization might suggest.
Key Investor Takeaways
- EPS beat with resilient profitability: Q4 EPS $0.14 vs $0.11 consensus; full-year EBITDA margin 40.4%
- Unit economics inflection: Q4 average revenue per visit +11% year over year to $316 after multiple quarters of pressure
- $164 million in cash, D/E 0.20x — significant M&A and growth optionality
- OrangeTwist partnership active: operational priorities defined across growth, wellness, and efficiency initiatives
- SBC Wellness 2.0 targeting Japan’s $34 billion longevity market, with 160 corporate clients and 50,000 individuals enrolled
SBC Medical is not a clinic operator in the traditional sense. We are a management platform. We provide the infrastructure, systems, procurement relationships, and clinical training that allow affiliated medical corporations to deliver high-quality care at scale.
Our network has grown to 283 locations over 25 years. The model consistently generates EBITDA margins above 40% while remaining capital-light. The structure works because we separate the management of medicine from the practice of it. That separation makes the business scalable and positioned to expand across markets.
The recovery in average revenue per visit is the clearest signal of improving unit economics.
Our pricing and promotion strategy has become more disciplined. At the same time, our multi-brand strategy is beginning to contribute. NEO Skin Clinic attracts higher-spending customers, while JUN CLINIC brings premium laser expertise.
When customer visits are also growing, you get both volume and price moving together. We are seeing these changes drive sustainable improvement in unit economics. If that continues, it becomes a powerful driver of long-term growth.
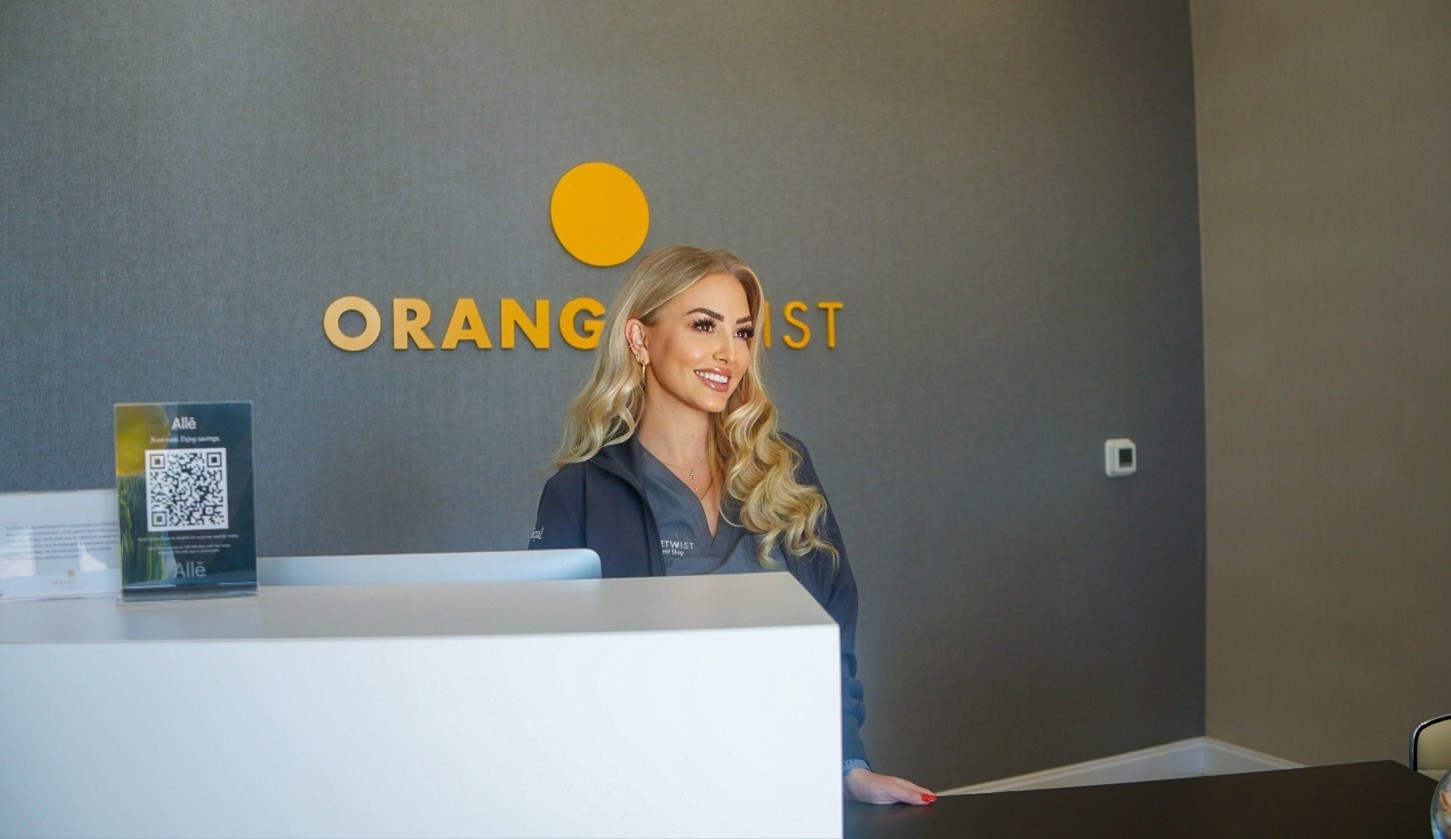
Early operational engagement with the OrangeTwist team has already identified clear opportunities to accelerate growth and improve efficiency.
Three priorities are driving the partnership forward. First, applying SBC’s proven marketing and customer acquisition systems to scale OrangeTwist. Second, developing longevity and wellness offerings in the U.S. Third, improving cost structure through AI-driven operational tools.
OrangeTwist delivers a premium customer experience. Our focus is scaling that model efficiently while preserving its core value.
Clint Carnell, Co-Founder and Director of OrangeTwist and former CEO of HydraFacial, a leading global skincare device company he led through its IPO, brings direct experience scaling premium healthcare brands in the U.S.
That experience significantly reduces execution risk when entering the U.S. market. Building clinics is one challenge. Building a scalable healthcare brand requires a different level of operational and strategic expertise. OrangeTwist brings both.
The U.S. market is large but fragmented, dominated by independent operators with inconsistent standards. What we bring is system-level consistency.
Our repeat customer rate is 72%, reflecting clinical protocols and customer management systems refined over 25 years and millions of patient visits. That consistency drives predictable economics and stronger customer lifetime value.
Few operators have built systems that replicate quality at scale. That is the system we are introducing into the U.S. market.
2025 was a year of deliberate transition. Full-year revenue came in at $174 million, down 15%. That decline was intentional.
We revised our franchise fee structure in April 2025 and exited non-core businesses. Those two decisions alone accounted for roughly $41 million in revenue impact, not operational weakness.
Net income grew 9% to $51 million while EBITDA margin held at 40.4%. The underlying earnings power of the business remained intact.
Phase 1 focuses on building optionality rather than scale. We expect approximately 30 international locations by the end of 2026, with OrangeTwist representing a meaningful portion.
Progress depends on identifying which markets, models, and partners can scale profitably. OrangeTwist is providing that operational insight.
With $164 million in cash and minimal debt, we have substantial flexibility for opportunistic M&A in Japan while funding disciplined international expansion.
Our objective is to establish leading positions across multiple healthcare categories in Japan by 2035. Capital deployment supports that goal. Internationally, we will scale selectively as Phase 2 opportunities become clear.
Our CTO, Sheng-FU Hsiao, brings proven experience automating call centers and modernizing large-scale systems.
We are focusing on three areas: headquarters efficiency, call center automation, and clinic-level optimization. We are building an operating model where costs scale more slowly than revenue. That is how we achieve durable scalability.
The longevity market, focused on preventive and performance-based healthcare, is significantly larger than aesthetic medicine. In Japan, it is estimated at $34 billion versus $4 billion for aesthetics.
We currently work with 160 corporate clients covering 50,000 individuals through SBC Wellness 2.0. This infrastructure is already established and expanding. Initially, this functions as a customer acquisition channel. Over time, it is expected to evolve into a high-margin recurring revenue stream while reducing customer acquisition costs.
In aesthetic medicine, customer trust directly drives retention and lifetime value.
Our repeat visit rate is 72%, reflecting consistent clinical quality across the network. Our advisors, including Dr. Youn Seongjae in Korea and Dr. Kim Sang-yub, are not symbolic relationships. They actively shape how we introduce and standardize treatments across the organization. Clinical quality, applied at scale across 283 locations, becomes a durable competitive advantage.
Our objective is to establish SBC as the most trusted name in aesthetic medicine globally.
We expect our clinic models to operate internationally, supported by AI-driven infrastructure, with longevity emerging as a new growth category in Japan.
We are a profitable, cash-rich company with a 25-year operating track record, improving unit economics, and multiple growth drivers. The foundation is in place for the next phase of value creation.