Analyst suggests the arrival of Tesla’s budget-friendly ‘Model Q’, and potentially a new China EV, following a meeting with the Tesla team
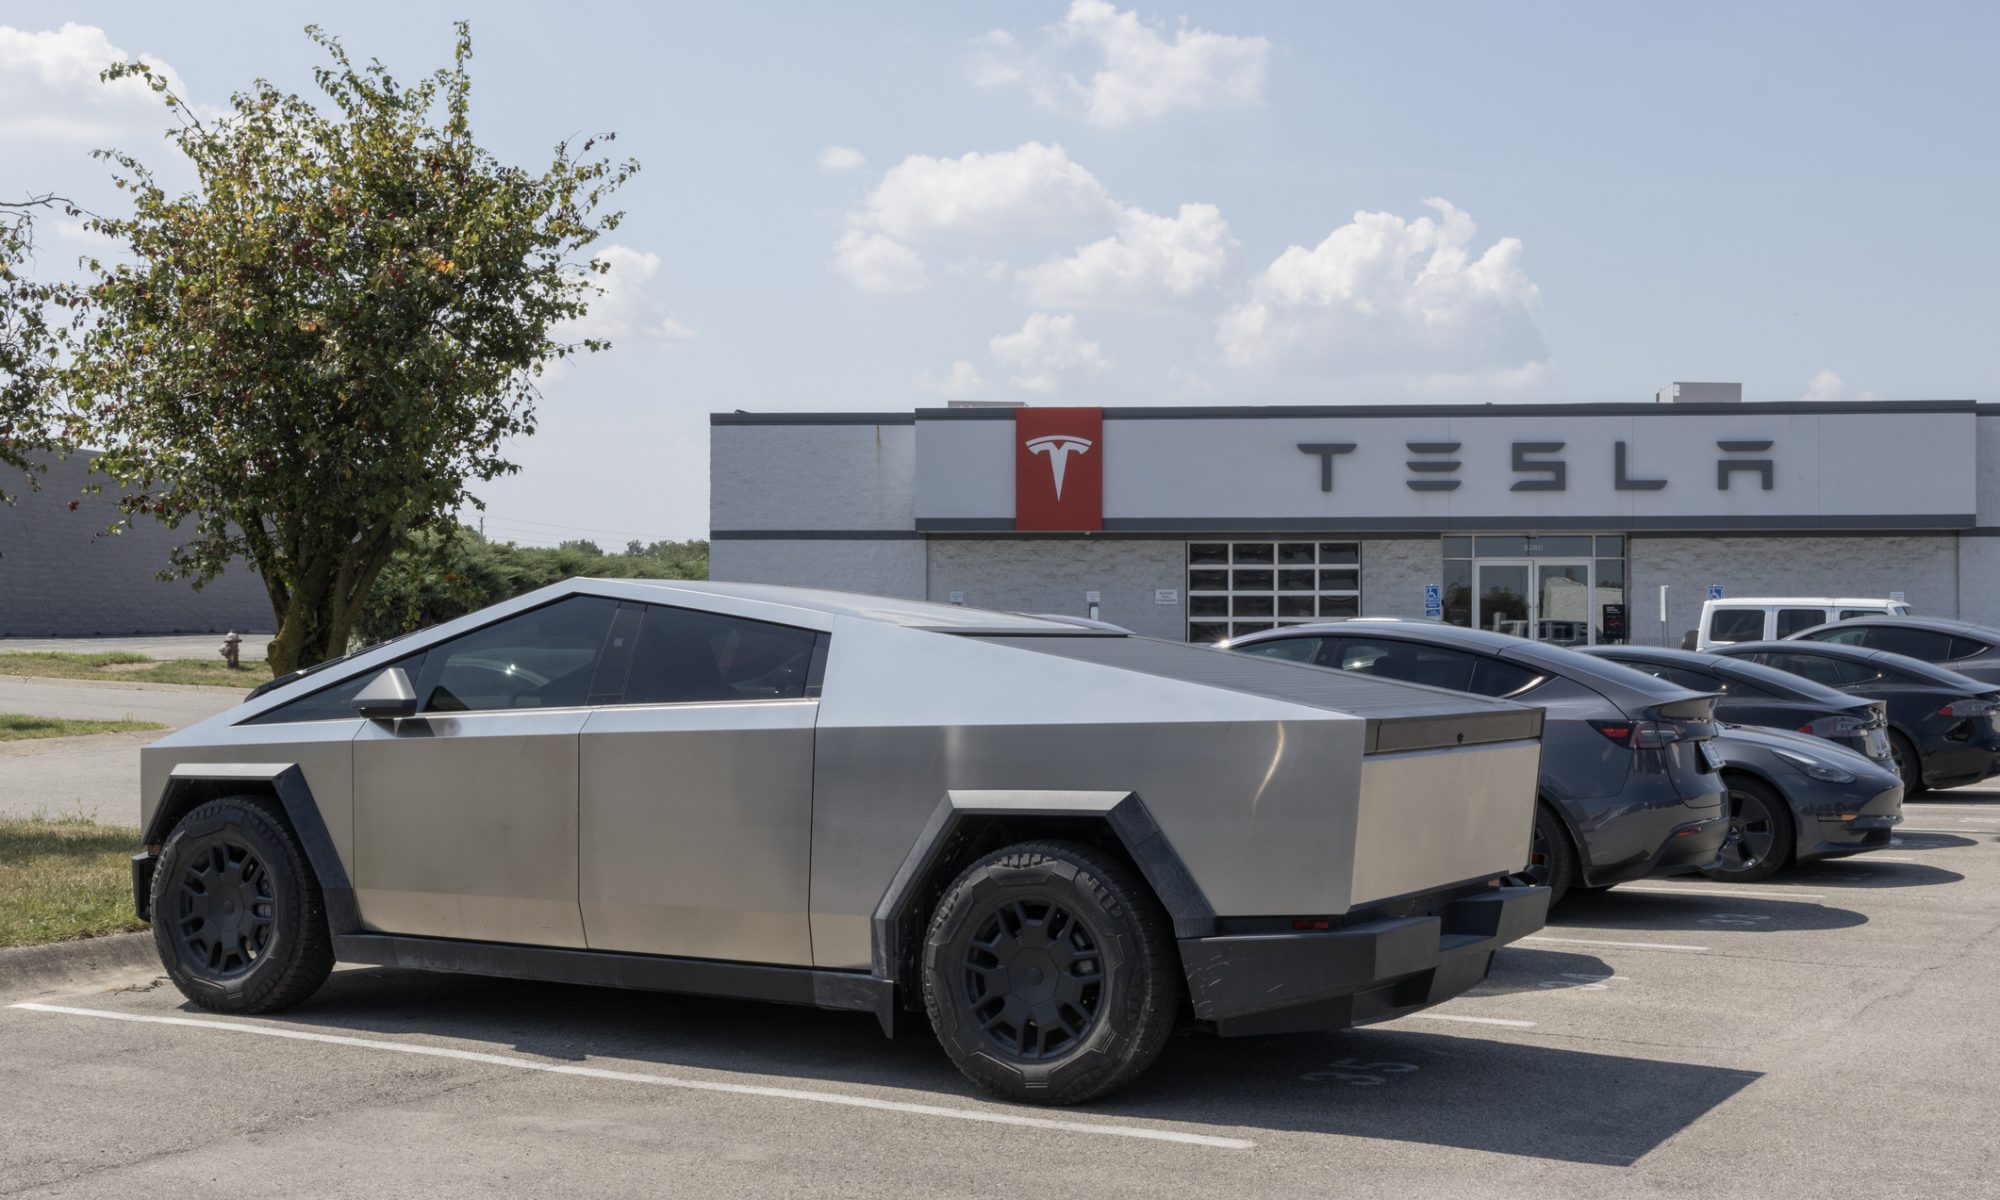
Tesla (TSLA) stock is seeing an uptick following Morgan Stanley’s decision to increase its price target from $310 to $400. The financial powerhouse continues to rate Tesla as Overweight and confirms the electric car producer as its first choice.
Deutsche Bank has increased its Tesla (TSLA) price forecast following informative investor discussions that provided insight into the company’s upcoming offerings.
The main focus of the meeting was on full self-driving (FSD), robotaxis, and Tesla’s Optimus robot. However, the dialogue with Tesla’s investors and Travis Axelrod, the head of investor relations, also touched on upcoming product developments.
Analyst Edison Yu revealed in a recent note that a new Tesla model, referred to as ‘Model Q’, is set to be launched in 1H25 and is expected to be priced under $30,000 with subsidies (or $37,499 if US EV tax credit is discontinued). Yu also anticipates that Tesla will introduce other vehicles aimed at increasing its TAM (total addressable market), including a potential 3-row longer wheelbase Model Y variant specifically for the Chinese market.
There’s ongoing speculation around a Tesla van for commuters and cargo. The unveiling of the Model Q name and a new Model Y variant in China took many by surprise. Based on these recent product reveals and other Tesla initiatives, both Yu and Deutsche Bank have lifted their Tesla price target from $370 to $295.
Yu is the most recent analyst to emphasize the burgeoning potential of Tesla’s total addressable market (TAM), which is set to thrive due to new products in the pipeline. Earlier, BofA raised its Tesla price objective subsequent to a visit to the Giga Austin factory, postulating that the forthcoming, wallet-friendly electric vehicle (EV) will bolster Tesla’s TAM. Priced under $30,000, this model promises to leverage cost reductions via simplified features and economies of scale. BofA anticipates the unveiling of additional models by 2025.
Moreover, in a post-investor meeting discussion with Axelrod, Yu revealed Tesla’s aspirations to achieve a volume growth of 25%-30% in the following year, relying on their capacity to ramp-up production in existing facilities.
Notably, apprehensions have emerged around Tesla’s EV demand concerning volume growth. Goldman analyst Mark Delaney adjusted his Q4 delivery forecast downwards for Tesla, hinting at a stagnation in growth by 2024. However, the potential rollout of new and more affordable products, regardless of the possible discontinuation of the federal tax credit in the US, has generated optimism among analysts including Yu and BofA’s John Murphy.
On the more ambitious side of Tesla’s projects, Yu expects the testing of Tesla’s Robotaxi to kick off next year in California and Texas, implementing “teleoperators” for utmost safety. He also expressed optimism about Tesla’s upcoming “unsupervised” Full Self-Driving (FSD) rollout expected between Q2 and Q3 of next year. While Tesla has previously fallen short of its bold targets, Yu believes that this time may be different due to anticipated federal self-driving rules from the National Highway Traffic Safety Administration (NHTSA) likely to alleviate regulatory restrictions. Predicting that the Robotaxi service will also launch internationally, Yu foresees a surge in Robotaxi forecast.