VivoPower Turns EBITDA Positive On Norway Data Center Deal
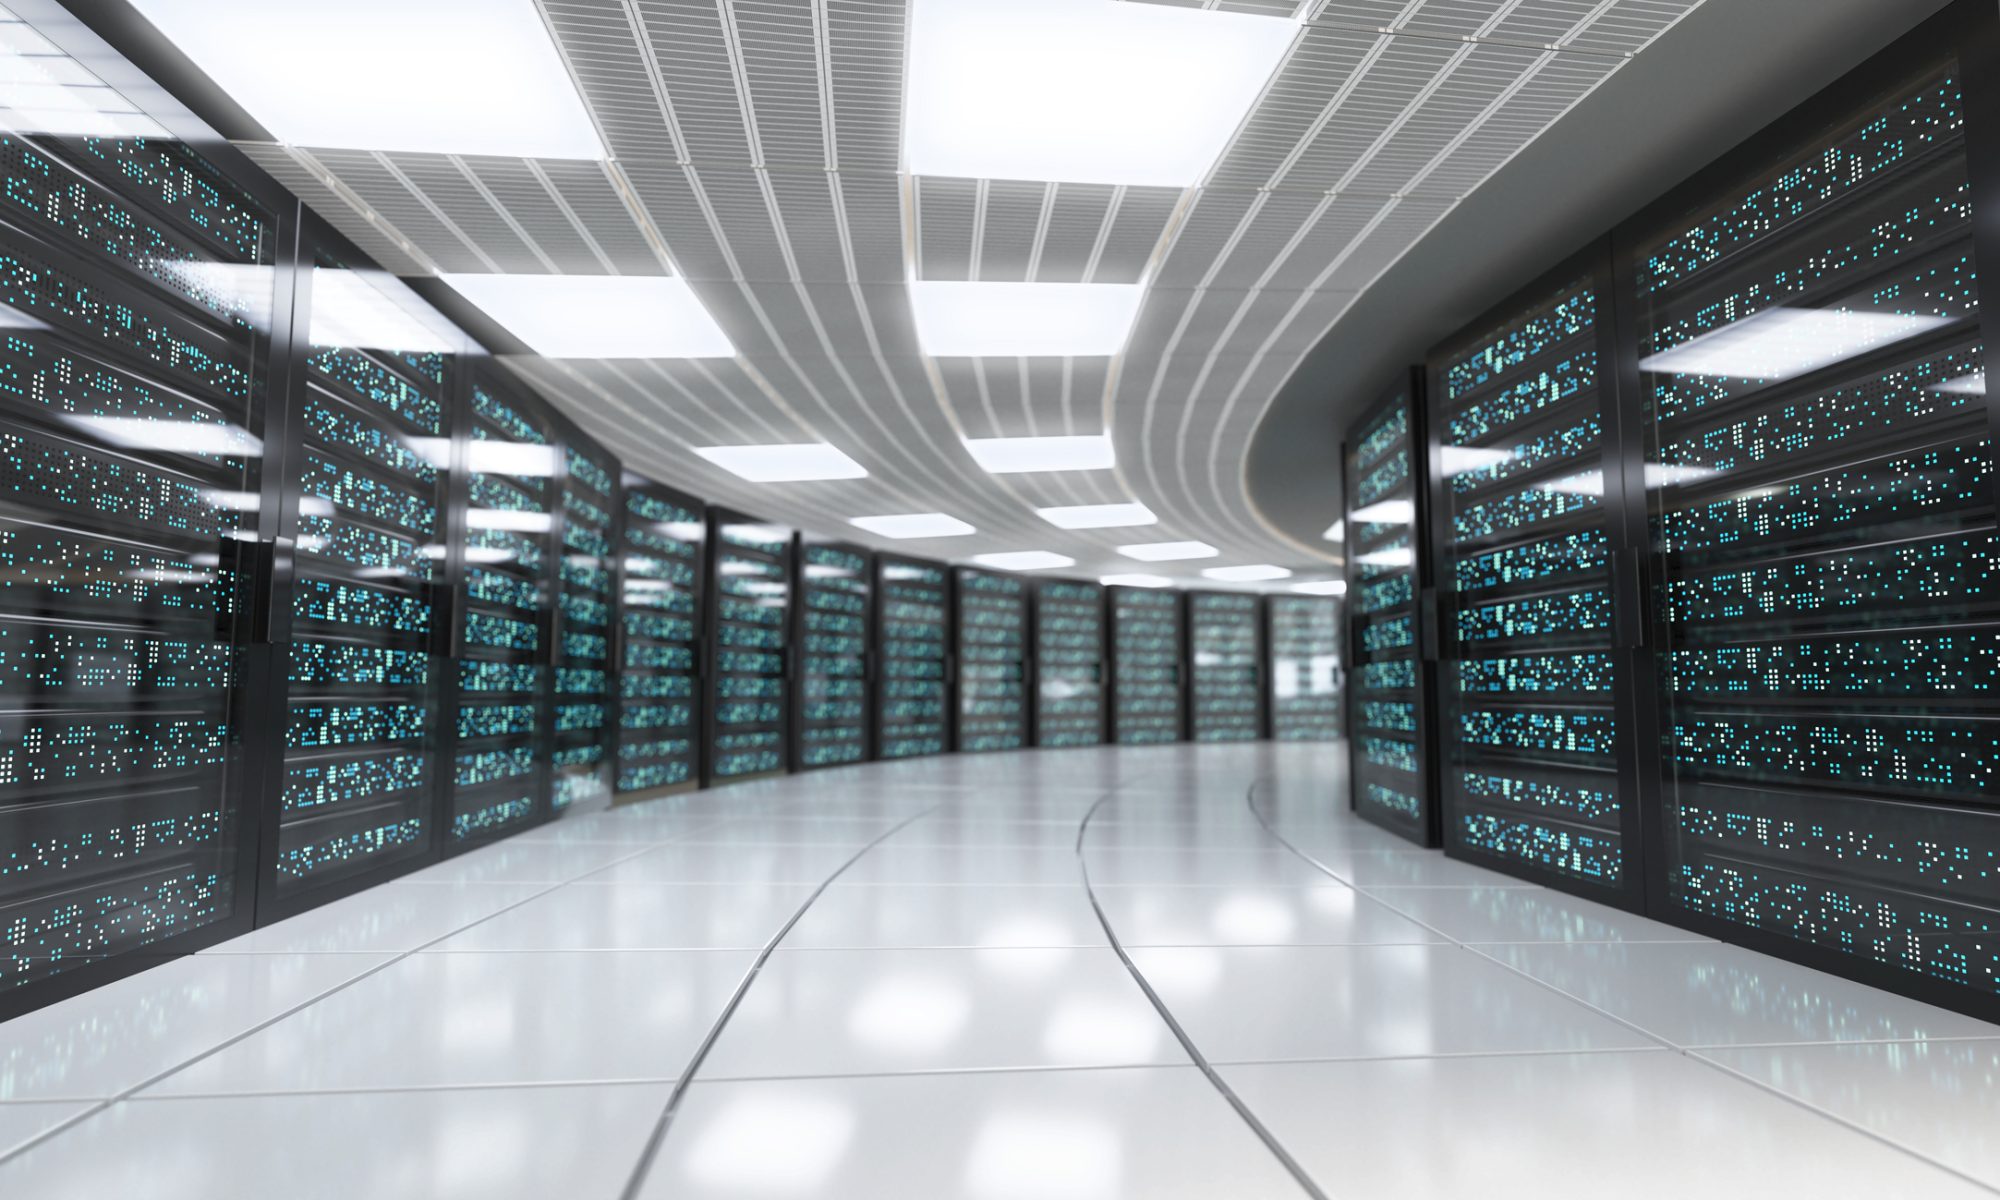
VivoPower (NASDAQ: VIVO) has closed and fully funded a 41 million acquisition of a 41.5MW energized data center in Norway, instantly flipping the group to pro forma EBITDA profitability. The asset is expected to contribute about 31 million in annualized revenue and roughly 10 million in annualized EBITDA, compared with just 0.1 million in revenue and an 8.2 million EBITDA loss for the year ended June 30, 2025, pre‑deal.
Asset profile and upside
The facility currently has 41.5MW of energized capacity and runs on 100% hydro power at an electricity cost below 0.035/kWh, giving it a structural cost advantage versus many global peers. The site has potential to add a further ~40MW subject to regulatory approvals, taking total capacity above 80MW and aligning with VivoPower’s longer‑term plan to pivot the asset from blockchain co‑hosting toward higher‑value “sovereign AI” and HPC compute.
Deal structure and valuation
The 41 million price tag implies an attractive ~4x pro forma EBITDA multiple based on the 10 million annual EBITDA contribution, which management calls “disciplined” in the current data center M&A environment. Importantly for existing shareholders, the acquisition was fully funded without an equity raise, relying instead on a mix of vendor finance and previously outlined structured capital, avoiding immediate dilution.
Strategic pivot to digital infrastructure
The acquisition builds on a December 2025 heads of agreement for a >40MW energized Norwegian data center that VivoPower initially flagged as a path back to profitability through its Caret Digital “power‑to‑X” strategy. With the transaction now closed, the company plans to shift focus from deal execution to asset optimization—driving utilization, improving tenant mix, and progressively repositioning the facility from crypto‑centric workloads to AI, cloud and other higher‑margin digital infrastructure use cases.
Investor perspective and peers
For investors, the Norway data center is a genuine step‑change: on paper, it turns a small, loss‑making sustainable‑energy group into an EBITDA‑positive digital infrastructure platform with a long‑duration, low‑cost power asset in a climate‑advantaged Nordic jurisdiction. The flip side is that VivoPower still carries a weak overall financial health profile and has been burning cash, so execution on lease‑up, AI pivot and balance‑sheet repair will be critical as it tries to compete with better‑capitalized data‑center and AI‑infra names like Equinix (EQIX), Digital Realty (DLR) and hyperscaler‑aligned developers.