Artivion Bets Big on Aortic Arch, Locking In Endospan’s NEXUS System
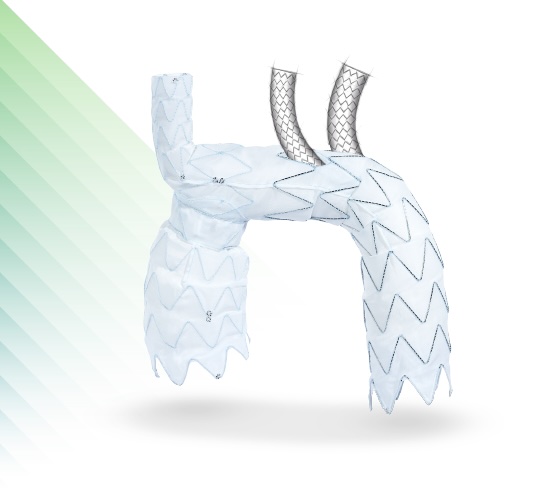
Artivion, Inc. (NYSE: AORT) is paying about $135 million upfront to acquire Endospan Ltd., locking in the FDA‑approved NEXUS Aortic Arch System and significantly strengthening its aortic arch portfolio. The deal is structured as a $175 million all‑cash base purchase price minus previously extended loans, plus up to $200 million in future earn‑outs tied to NEXUS performance.
What the Endospan deal adds
Endospan is an Israel‑based developer of endovascular solutions for aortic arch disease, led by the NEXUS Aortic Arch Stent Graft System, which recently received U.S. FDA PMA approval. By acquiring Endospan, Artivion gains full ownership of NEXUS and its pipeline, extending its reach into minimally invasive aortic arch repair for patients who previously had limited options.
Key financial terms
- Base purchase price: $175 million, paid in cash.
- Net upfront payment: about $135 million after deducting outstanding Endospan loans Artivion had already provided.
- Contingent consideration: up to $200 million payable roughly two years post‑closing, depending on NEXUS commercial performance.
- Funding: primarily via borrowings under Artivion’s delayed‑draw term loan facility, increasing leverage but avoiding equity dilution.
Strategic fit in aortic arch
Artivion sees this acquisition as central to its ambition to be the go‑to company for aortic arch repair, combining NEXUS with its existing AMDS device and the future Arcevo LSA platform. Management has stated that with AMDS, NEXUS, and Arcevo LSA, Artivion aims to be the only player offering a complete portfolio across open, hybrid, and endovascular arch procedures.
The company plans to leverage its global commercial network to accelerate NEXUS adoption and expand access to advanced endovascular options for complex aortic arch patients.
Investor view on AORT
For investors in Artivion, the Endospan acquisition offers meaningful strategic upside alongside higher financial commitments. Artivion gains a differentiated, newly approved device in a high‑value niche, but it also takes on more debt and a sizable potential earn‑out, making execution on NEXUS training, reimbursement, and adoption critical to justify the price tag.