


Archer Aviation Climbs 11% After Snapping Up Boeing’s Air-Taxi and Drone Units
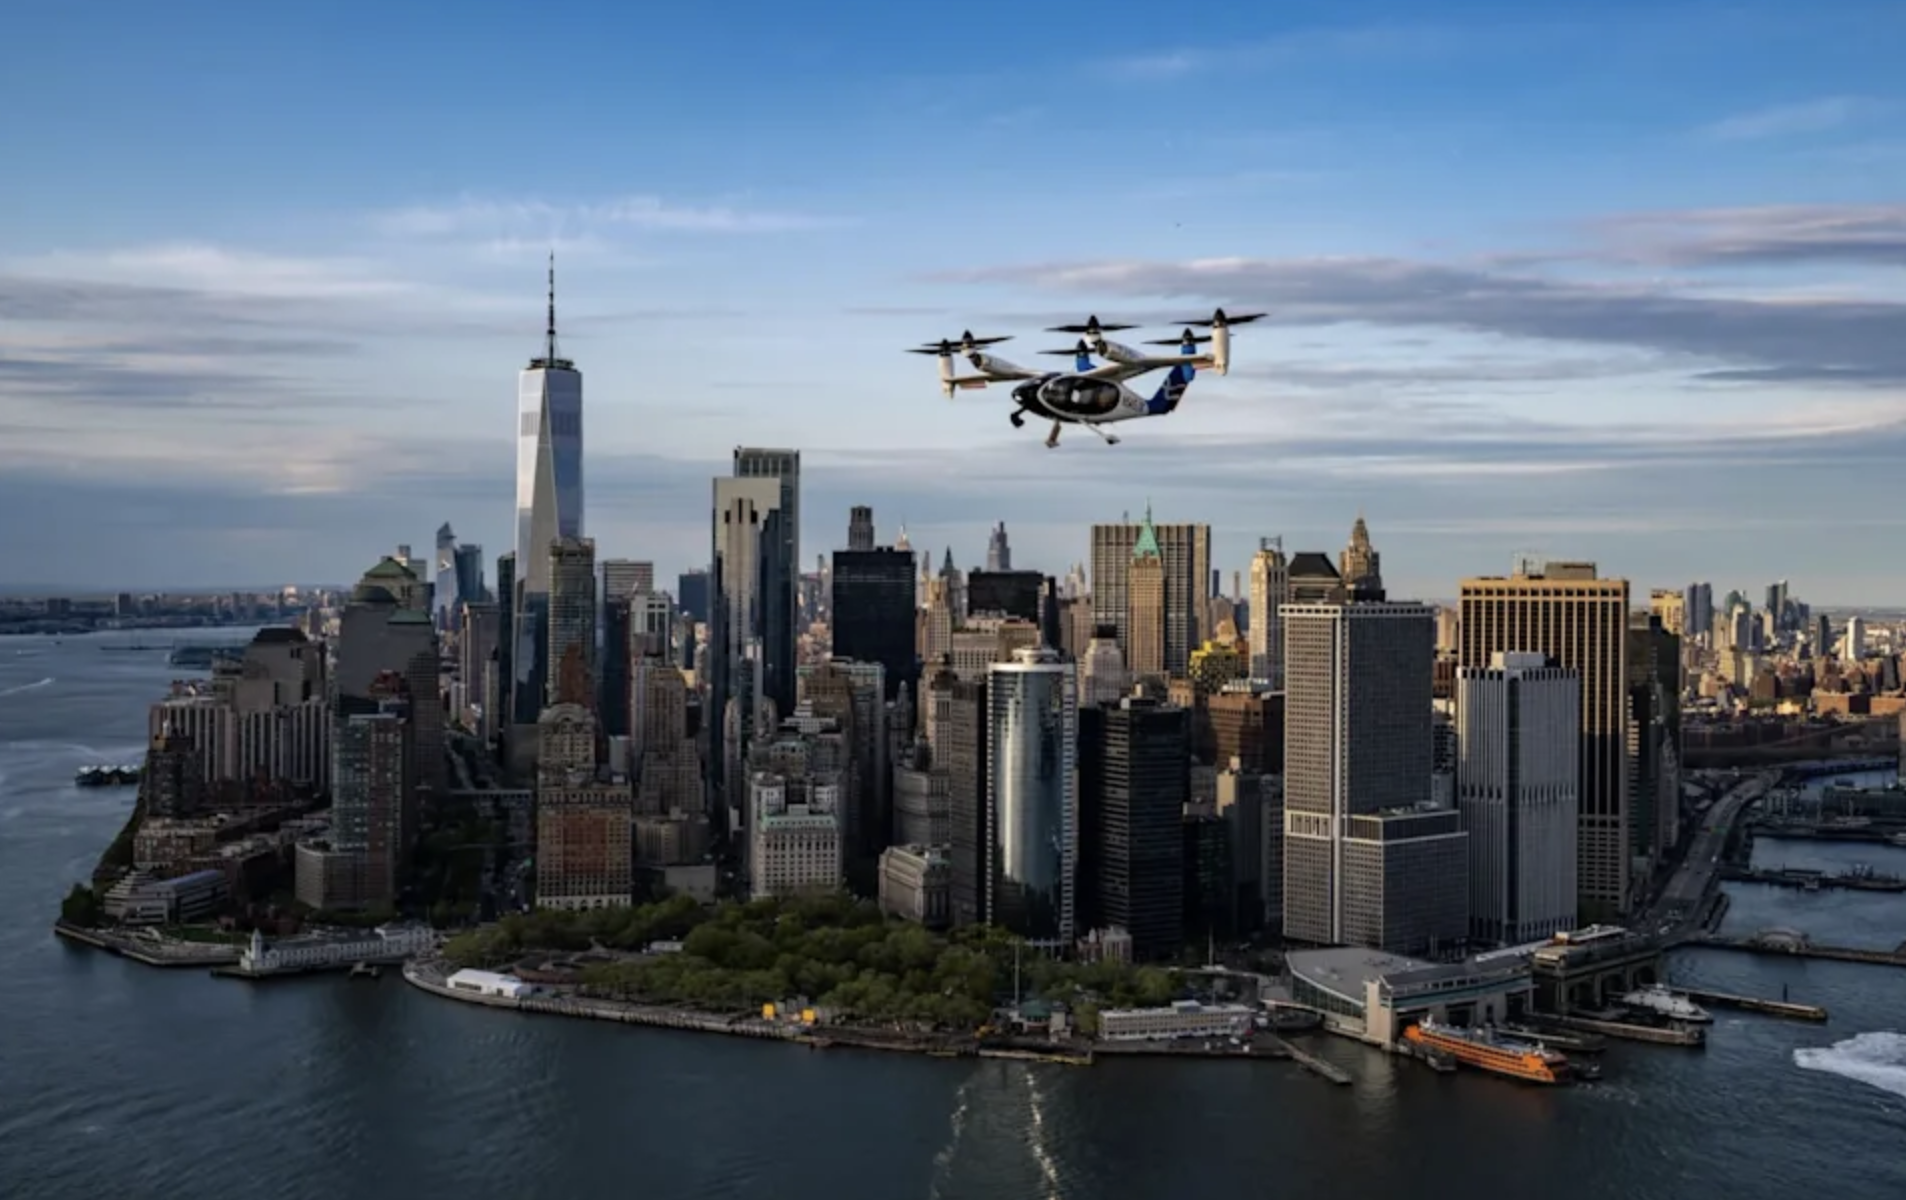
Archer Aviation (ACHR) surged as much as 20% Monday before settling up about 11% near $6.21, after the eVTOL maker agreed to acquire three aviation-technology businesses from Boeing in exchange for a stake of nearly 20%. The deal dramatically expands Archer’s reach beyond air taxis, and investors piled in ahead of the company’s Q2 earnings call the same afternoon.
Key Points
- The deal: ACHR is acquiring Wisk Aero, SkyGrid, and Insitu from Boeing, handing Boeing a nearly 20% equity stake in Archer.
- The strategy: The acquisition pushes Archer beyond urban air taxis into autonomy and the defense/drone market.
- The move: Shares spiked ~20% intraday, then settled around +11% to $6.21 on heavy volume — nearly 118M shares vs. a ~42M average.
- The second catalyst: Archer reports Q2 2026 earnings today at 5 PM EDT.
- The balance sheet: The company holds roughly $1.78 billion in cash, but it remains pre-revenue and loss-making (trailing revenue under $2M, net loss ~$743M).
- The Street: Canaccord Genuity rates it Buy; the average target near $10.50 sits well above the current price, though estimates range from $4.50 to $18.
- The volatility: ACHR carries a beta above 3 and trades far below its 52-week high of $14.62.
A Deal That Reshapes the Story
Because investors have long questioned how Archer would scale beyond a single air-taxi product, the Boeing transaction directly addresses that concern. Specifically, the company is absorbing Wisk Aero (an autonomous-flight developer), SkyGrid (airspace-management software), and Insitu (a established drone and unmanned-systems business). Consequently, ACHR gains both advanced autonomy technology and a foothold in defense, and it diversifies a revenue mix that previously hinged almost entirely on future air-taxi launches. Moreover, Boeing’s nearly 20% stake ties an aerospace heavyweight to Archer’s roadmap, which the market read as a meaningful vote of confidence.
Growth Potential Meets a Cash-Burn Reality
Although the strategic logic looks compelling, investors shouldn’t overlook Archer’s financial profile. The company still generates almost no revenue — under $2 million on a trailing basis — while it burns cash rapidly, posting a net loss near $743 million over the past year. Fortunately, Archer entered the deal with a solid cushion of roughly $1.78 billion in cash, so it can fund integration and continued development for now. Even so, the eVTOL maker must still clear FAA certification, ramp manufacturing, and launch commercial service before the story translates into real sales. Therefore, today’s pop reflects optimism about the expanded opportunity rather than current fundamentals.
Earnings Add a Second Catalyst
Adding to the drama, ACHR reports Q2 2026 results today at 5 PM EDT, so the Boeing news and the earnings print land in the same session. As a result, management will likely field questions not only on the quarter but also on how it plans to integrate three new businesses and fund the combined operation. Furthermore, investors will listen closely for updates on certification progress, the 2026 air-taxi launch timeline, and the Anduril defense partnership. Ultimately, the call could either reinforce Monday’s rally or expose the execution risks that have long shadowed the stock.
What to Watch Next
Looking ahead, investors should first parse today’s earnings commentary for concrete detail on the Boeing deal’s terms, expected revenue contribution, and integration timeline. Next, watch Archer’s cash burn and any guidance on when the acquired units — particularly Insitu’s drone business — could generate meaningful sales. Finally, keep an eye on FAA certification milestones and manufacturing progress, since those remain the true gatekeepers to commercialization. Ultimately, if Archer Aviation (ACHR) converts this expanded platform into a credible path to revenue, today’s jump could mark a genuine inflection rather than a headline-driven spike.












