SBC Medical Q2 Revenue Rises 13% as Net Income Climbs 335%
Operating income, EBITDA and EPS all accelerated in the second quarter, while the clinic network SBC supports expanded to 287 locations.
SBC Medical Group Holdings Incorporated (Nasdaq: SBC), a Medical Services Organization providing management support to medical institutions in Japan and abroad, reported second-quarter 2026 results showing growth across every headline financial metric alongside continued expansion of the clinic network it supports.
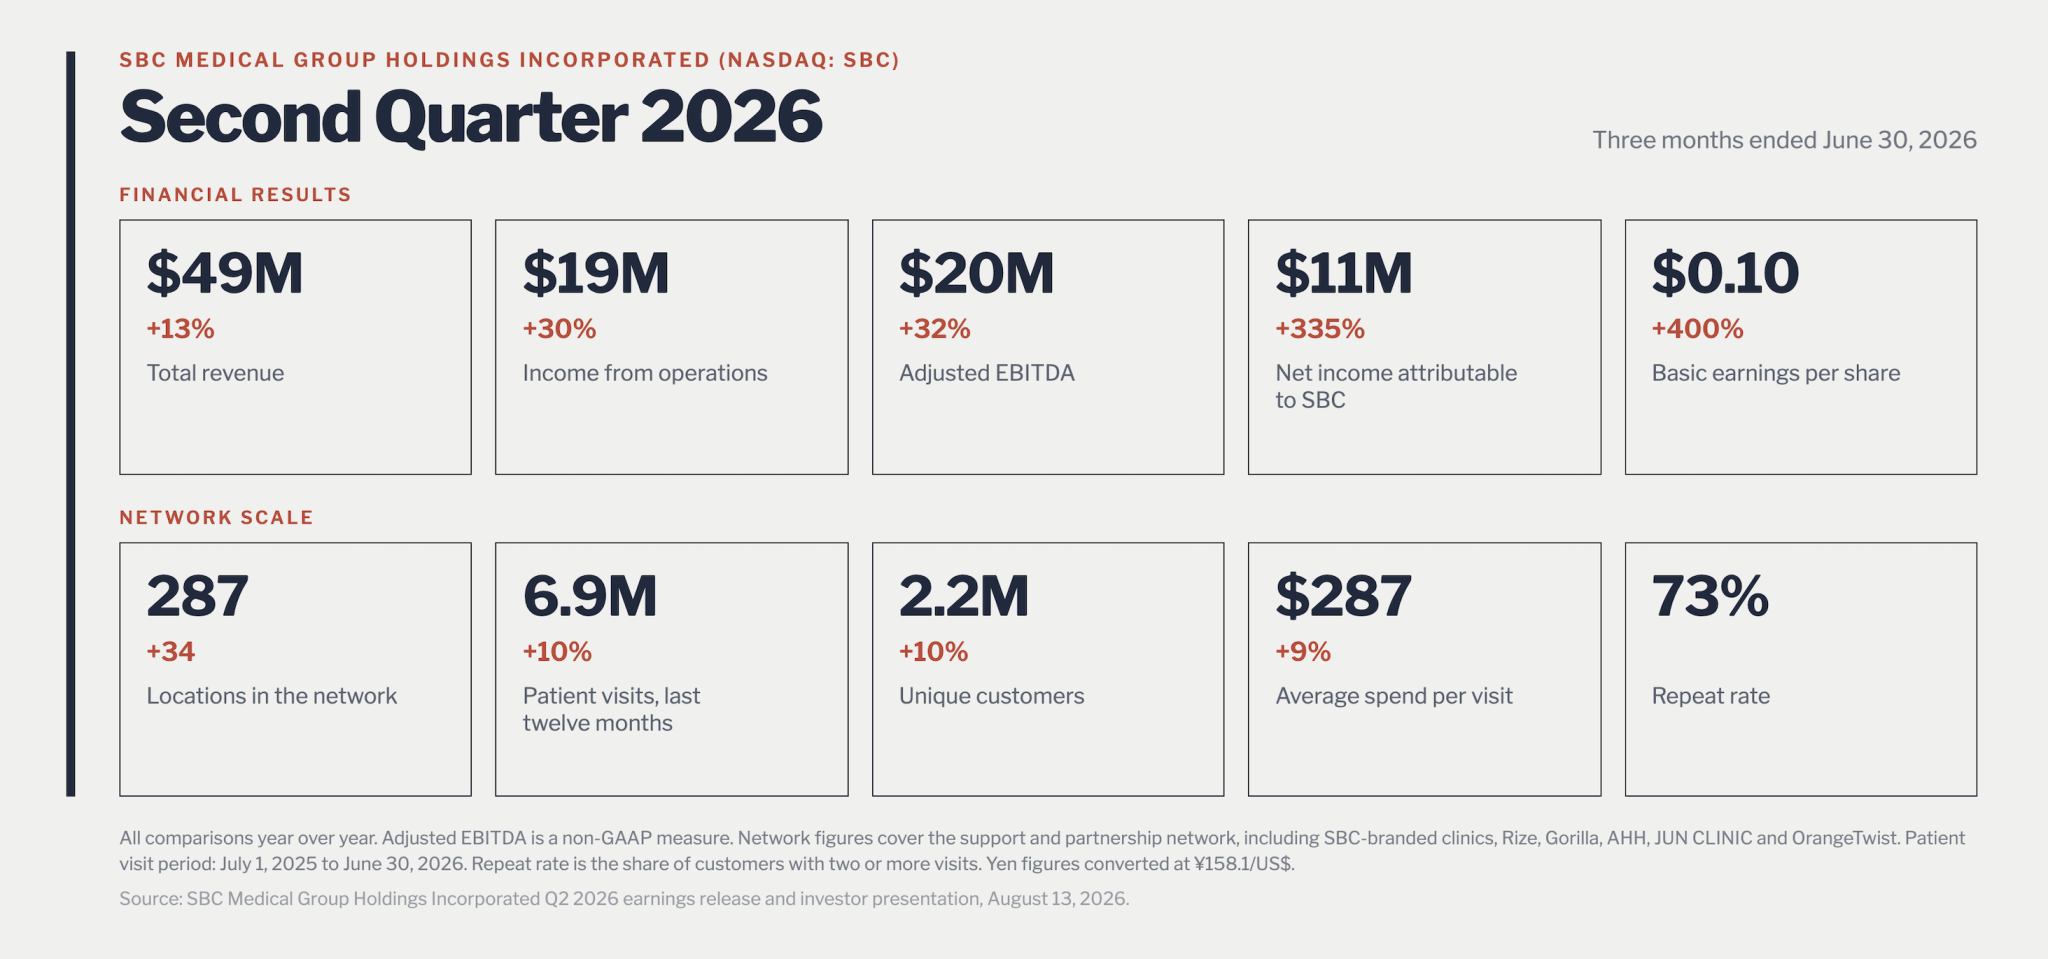
For the three months ended June 30, total revenue reached $49 million, up 13% year over year, absorbing a $4.7 million foreign exchange headwind from yen depreciation. Gross margin expanded to 73% from 69%, and income from operations increased 30% to $19 million.
Profit growth outpaced the top line. Net income attributable to SBC increased 335% to $11 million, compared with $2 million in the prior-year quarter. Net income margin reached 22%, up 16 percentage points year over year. Basic earnings per share increased 400% to $0.10 from $0.02, and annualized return on equity improved to 16% from 4%.
Adjusted EBITDA was $20 million, up 32%, with Adjusted EBITDA margin of 41% against 35% a year earlier. Adjusted EBITDA and Adjusted EBITDA margin are non-GAAP measures.
Looking ahead, the company is revising its service fee levels in stages, which is expected to increase service fees by approximately $15 million annually if the impact is realized for a full year.
Chairman and CEO Yoshiyuki Aikawa described the quarter as the start of a new phase for the company, pointing to the completion of structural reforms undertaken in 2025 and the emergence of multiple growth engines operating in parallel.
Clinic Network and Patient Volumes Expand
The medical corporations SBC supports also continued to grow. The company’s support and partnership network reached 287 locations as of June 30, an increase of 34 locations, or 13%, from a year earlier. That network spans SBC-branded clinics, Rize Clinic, Gorilla Clinic, AHH Clinic, JUN CLINIC and OrangeTwist.
Last-twelve-month patient visits at the supported clinics reached 6.9 million, up 10%, across 2.2 million unique customers, also up 10%. Average spend per visit rose 9% to $287 in the quarter, and the repeat rate across the applicable brands was 73%.
Revenue at the clinics SBC supports totaled $582 million for the first half, up 11% year over year, with same-clinic revenue up 6% to $543 million. First-half transaction value in aesthetic dermatology grew 19%, driven by adoption of higher-value treatments among existing customers.
Within SBC’s own results, management services revenue increased 150% year over year to $13 million, supported by expansion of the points business following a change in operating policy and by revisions to certain service fees.
AI-Enabled Services Support Higher Fees
SBC is building AI into the operating platform it provides to affiliated clinics, drawing on more than 26 years of accumulated management data. Released tools include an AI chatbot for 24/7 inquiry handling, the TalkBridge English and Chinese interpretation service, AI-assisted site selection for new clinic openings, and an internal knowledge-sharing system. An AI-enabled call center is planned for release in 2026, with marketing AI rolling out in phases.
Aikawa said fee revisions for call center services provided to five affiliated medical corporations, combined with separate revisions reflecting expanded support for Rize Clinic and Gorilla Clinic, are expected to increase service fees by approximately $15 million annually if the impact is realized for a full year, converted at ¥158.1/US$. The company attributes roughly $11 million of that to the call center and roughly $4 million to the Gorilla and Rize support expansion. Call center fee revisions took effect from July and the Gorilla and Rize revisions from June.
Balance Sheet Supports the Next Phase
SBC ended June with $184 million in cash and cash equivalents, up from $164 million at December 31, 2025. Total stockholders’ equity was $280 million, compared with $263 million at year-end. For the first six months of 2026, net cash provided by operating activities was $32 million, against $6 million used in operating activities in the first half of 2025.
Management outlined four growth strategies: deepening the multi-brand strategy in aesthetic dermatology, expanding non-aesthetic healthcare as a second growth engine, extending internationally through the OrangeTwist collaboration in the United States and an ASEAN rollout anchored in Thailand, and scaling AI-enabled services across the platform. The company is also preparing to enter the longevity market, with a dedicated center planned for 2027.
On the capital markets side, SBC noted free float expanded 8% year over year as of June, shareholder accounts grew 4.7x year over year as of July, and the company has more than 10 investor conferences scheduled between August and December, including New York and Hong Kong.
Disclaimer
This communication was produced by Prism MarketView. The information contained on this is ‘Paid Advertising’ for purposes of Section 17(b) of the Securities Act of 1933, as amended (together with the rules and regulations there under, the “Securities Act”). “PRISM” and its affiliates are compensated by respective clients for publicizing information relating to its client’s securities. For more information in terms of compensation received for services provided by PRISM see the pertinent advertising materials relating to the respective client. By accessing this Site and any pages thereof, you agree to be bound by the Terms of Use and Privacy Policy…