


Nike Bets on a 34-Year-Old Arnault Heir Days Before NKE Exits the S&P 100
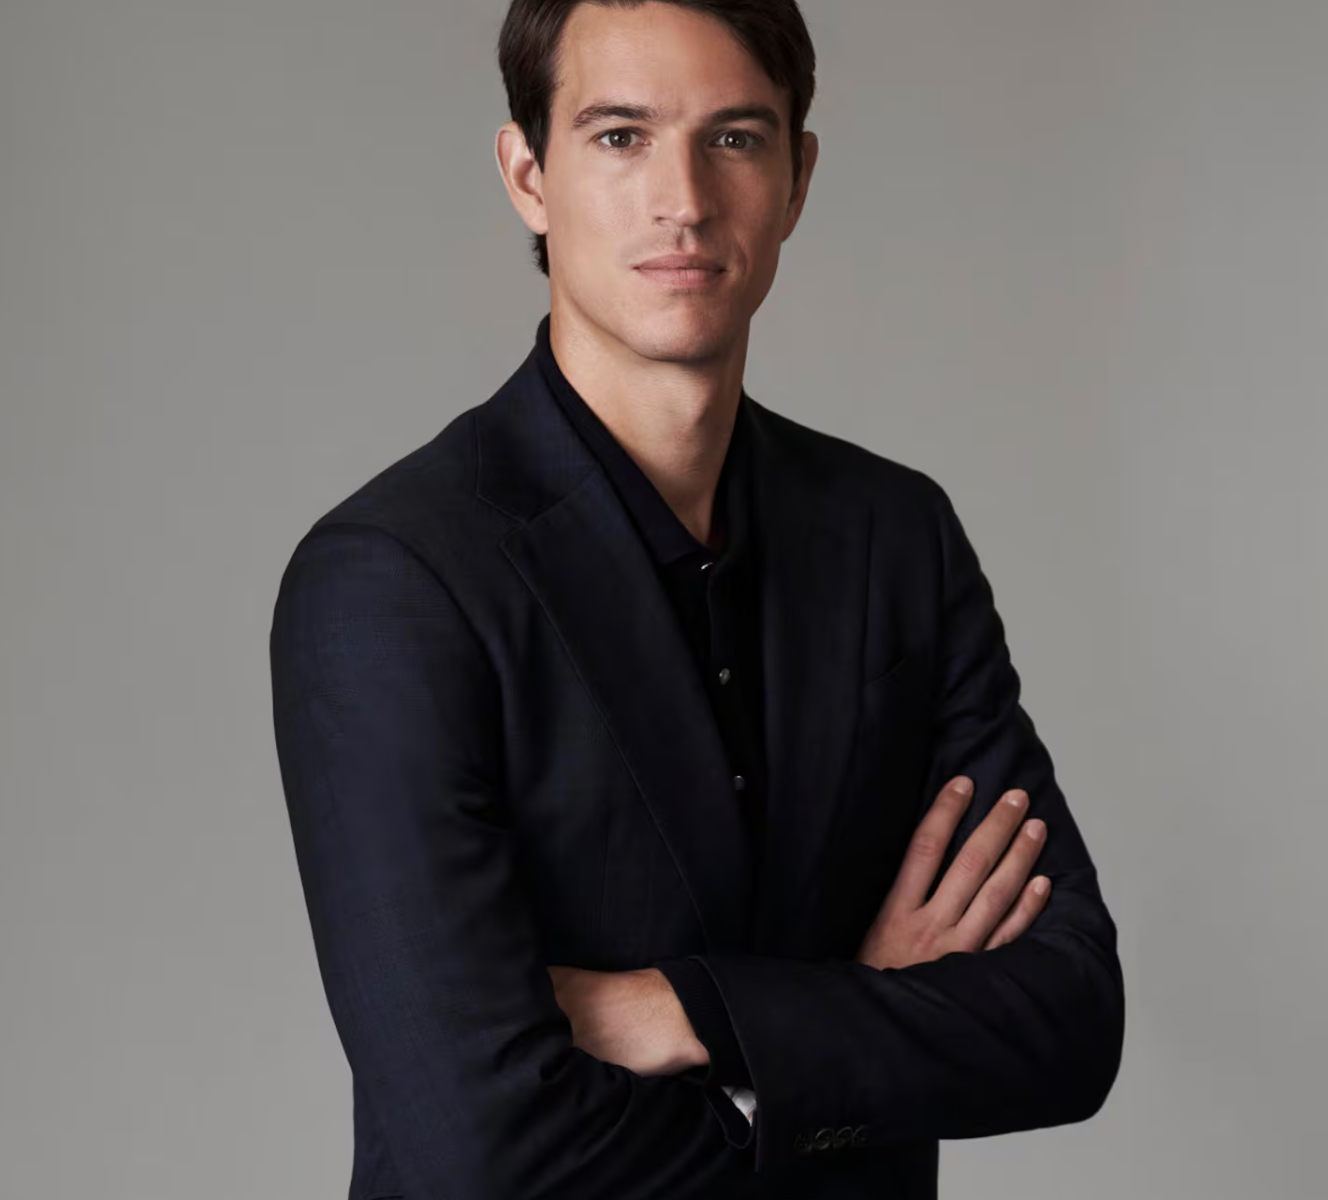
NIKE, Inc. (NYSE: NKE) handed a board seat to Alexandre Arnault, the 34-year-old son of LVMH chief Bernard Arnault, effective September 15 — and the timing tells the story. Six days later, on September 21, the swoosh formally drops out of the S&P 100 after 18 years in the index. Consequently, Nike recruited luxury’s most-watched young operator at precisely the moment Wall Street stopped treating it as a blue chip.
Key Points
- Nike expanded its board to 12 directors to seat Arnault, per the company’s 8-K filing. Committee assignments remain undetermined.
- Arnault currently helps run LVMH’s wines and spirits division. Previously, he served as CEO of Rimowa and led products and communications at Tiffany & Co.
- NKE has shed more than $200 billion in market value since its November 2021 peak of roughly $264 billion. The stock trades near $35.81, down roughly 80% from its high.
- Nike leaves the S&P 100 on September 21. Dell Technologies (DELL), Palo Alto Networks (PANW), Arista Networks (ANET) and Sandisk (SNDK) take its place.
- Greater China sales have now declined for eight consecutive quarters, falling 17% on a constant-currency basis in the most recent period.
What Arnault Brings to the Nike Boardroom
Arnault built his reputation by dragging heritage brands into youth culture. At Rimowa, he rebuilt the retail footprint and struck collaborations with Supreme and Off-White. Then, at Tiffany, he pushed the 188-year-old jeweler into streetwear partnerships and fronted campaigns with Beyoncé and Jay-Z. Meanwhile, he cultivated a personal profile — NFT purchases, sneaker culture fluency — that reads far closer to Nike’s target consumer than a typical board nominee does.
Executive Chairman Mark Parker framed the appointment around exactly that track record. “Alexandre has earned a reputation for helping iconic global brands evolve, innovate and grow in a changing, complex marketplace,” Parker said. President and CEO Elliott Hill added that Arnault’s “experience across innovation, digital transformation and brand building will be an asset as we continue to strengthen our connection with consumers.” Notably, Arnault himself leaned on the athletic angle, calling himself “a lifelong sports enthusiast and runner.”
Why NKE Needed the Signal
The numbers explain the urgency. Nike closed fiscal 2026 with $46.4 billion in revenue, down 2% on a currency-neutral basis. Direct-to-consumer sales fell 6% to $17.7 billion, while digital dropped 12% — the very channel the previous administration bet the company on. Wholesale, by contrast, grew 6% to $27.5 billion, which validates Hill’s pivot back toward retail partners but also underscores how thoroughly the DTC thesis collapsed.
China remains the deepest wound. Eight straight quarters of decline have erased Nike’s growth engine, and tariff pressure plus domestic competitors like Anta and Li-Ning continue to squeeze the brand. As a result, Hill — a 32-year Nike veteran pulled out of retirement in 2024 to replace John Donahoe — inherited a turnaround with no easy lever left to pull.
How Investors Should Read the S&P 100 Exit
Index removal carries real mechanical consequences: funds tracking the S&P 100 must sell, which adds supply at already depressed levels. However, the symbolic damage cuts deeper. Nike spent 18 years among America’s 100 largest public companies, and four tech names now occupy the seat it vacated — a clean illustration of where index weight has migrated this cycle.
Still, contrarians see the exit differently. Forced selling into a name trading at roughly $53 billion in market cap, against $46 billion in annual revenue, sets up an asymmetric entry for anyone who believes Hill’s “Sport Offense” strategy eventually works.
What to Watch Next
First, watch for Arnault’s committee assignments, which Nike has not yet disclosed. Second, watch whether the appointment signals deeper LVMH collaboration — Louis Vuitton, Dior and Tiffany have all partnered with Nike before, and a luxury-adjacent product strategy would mark a genuine strategic turn rather than a governance refresh. Finally, watch the next China print. Until that line stops falling, board additions stay cosmetic.












