


Fermi Lands an Investment-Grade Hyperscaler for 600 MW at Project Matador, Replacing TensorWave and Sending Shares Up 16% Premarket
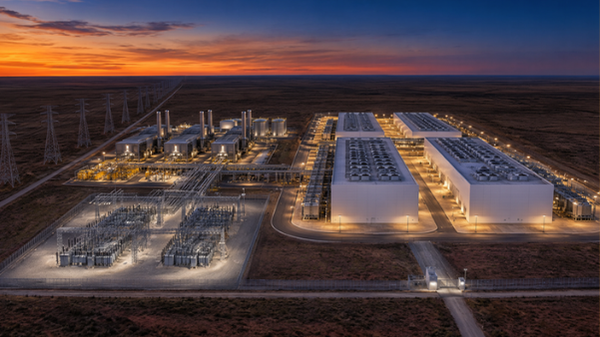
Fermi Inc. (NASDAQ: FRMI) shares jumped about 16% in premarket trading Thursday. The AI power developer said an undisclosed investment-grade hyperscaler committed more than $200 million up front to advance 600 megawatts of capacity at its Project Matador campus in Amarillo, Texas. Fermi also reported its third-quarter results and confirmed that its earlier TensorWave lease and the related AMD credit support agreement have been terminated. As a result, the stock builds on Wednesday’s rally and stands out in the PRISM AI Datacenter and Infrastructure Index.
Key Points
- An undisclosed investment-grade hyperscaler signed a $200 million prepayment agreement and a $15 million early construction agreement to advance an initial 600 MW, starting in 2027.
- A separate $90 million structural steel and building-materials purchase agreement is being finalized. Meanwhile, the two sides are still working toward a definitive long-term lease.
- Fermi and TensorWave ended their August 2026 lease, and the related AMD credit support agreement ended with it.
- Q3 net loss narrowed to $141.6 million from $346.8 million a year earlier. Fermi ended the quarter with $315.5 million in cash and restricted cash.
Fermi (FRMI) Trades One Anchor Tenant for a Bigger One
Fermi is building Project Matador, a private power grid and AI data-center campus in the Texas Panhandle. Its first anchor customer was TensorWave, an AI cloud provider, which signed a lease in August. AMD later agreed to back that lease with credit support. However, both agreements are now terminated.
In their place, Fermi signed up a much larger customer. The unnamed hyperscaler is investment grade, meaning its debt carries a strong credit rating, and it is committing capital before a final lease is in place. Its $200 million prepayment and $15 million early construction deal will fund work on an initial 600 MW, with development starting in 2027. The two companies are also finalizing a $90 million steel and building-materials agreement.
CEO Lee McIntire said hyperscalers “want sites that are ready with permitted power.” He added that Project Matador’s head start on power is a key reason the customer signed. Fermi said customer-funded construction lets it build “with little or no dilution,” meaning it shouldn’t have to sell as much new stock to pay for it.
Q3 Numbers: Still Pre-Revenue, but Losses Narrowed
Fermi doesn’t have revenue yet. Its third-quarter net loss was $141.6 million, or $0.22 per share, down from $346.8 million a year earlier. General and administrative expenses of $142.2 million made up nearly all of the loss. That figure included $65.8 million of non-cash stock compensation and $21.5 million of financial advisory fees paid in company stock.
At the same time, Fermi kept building. It invested $133.4 million in property and equipment during the quarter and $759.5 million over nine months, bringing net property and equipment to about $1.67 billion. Total buildout investment to date is nearly $1.7 billion. The company ended September with $315.5 million in cash and restricted cash, against $958.4 million in net debt.
Why the Deal Matters for FRMI
Fermi’s stock had lost about 80% of its value this year as investors worried about financing, insider selling and whether Matador would land solid customers. Last week, co-founder and largest shareholder Toby Neugebauer renewed his call for the company to pursue a sale or strategic partnership. He argued Fermi needed a partner with a lower cost of capital and a committed customer.
Today’s agreement addresses part of that argument. An investment-grade hyperscaler paying cash up front is a stronger anchor than the earlier lease. Analysts responded quickly: Cantor Fitzgerald reaffirmed its Overweight rating, and Evercore ISI reiterated its Buy rating.
Even so, risks remain. The long-term lease isn’t signed yet, the TensorWave exit shows how quickly deals can change, and stock-based pay and advisory fees continue to dilute existing shareholders.
What It Means for the PRISM AI Datacenter and Infrastructure Index
Fermi’s market value sits around $1.2 billion. The stock is still down roughly 78% since the PRISM AI Datacenter and Infrastructure Index launched on January 2, 2024. The company currently has 2.2 GW of capacity and plans to grow toward about 17 GW as it signs binding customer agreements.
PRISM MarketView has covered Fermi since its IPO filing to fund an 11 GW hyperscale campus and its nuclear agreements with Hyundai E&C and Doosan Enerbility. Today’s deal is the clearest sign yet that hyperscalers will commit capital to sites that already have permitted power.
Going forward, investors will watch for the definitive lease, the $90 million materials agreement, and how Fermi funds the next phase. Management is holding its earnings call at 9 a.m. ET today.












